


Swan’s Agentic Software Factory: Cygnet Evolved


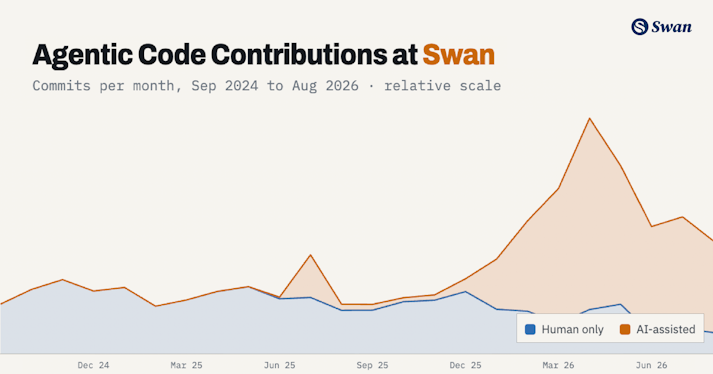
How Swan built an agentic software factory that finds production bugs, reaches consensus on the fix, opens the PR, and proves it works before a human merges.
In this article
The best Bitcoin-only IRAs in 2026 are the Swan Bitcoin IRA and the Unchained IRA. Swan charges 1% per trade, a monthly 0.02% platform fee ($20 minimum) and no setup fee. Unchained charges a 1.5% trading fee and $250 a year, and lets you hold two of the three keys to your IRA’s Bitcoin. River doesn’t offer an IRA of its own.
Below we compare their fees, custodians and account types as of October 2026, show what each costs on $10,000, $50,000 and $250,000, and cover the 2026 IRA contribution limits.
Swan Bitcoin IRA: Traditional and Roth IRAs. 1% on buys and sells, 0.02% a month of assets on platform ($20 minimum), $0 setup, transfer, rollover and closure fees. Custodian: Equity Trust. Trustpilot: 4.2 out of 5 from 1,376 reviews.
Unchained IRA: Traditional, Roth and SEP IRAs, plus Solo 401(k)s. 1.5% trading fee, $250 per IRA account a year, $2,000 trading minimum per transfer, rollover or contribution. Custodian: Fortis Bank. You hold two of the three multisig keys.
Both are Bitcoin-only: you can’t buy other coins inside them.
A Bitcoin IRA is an individual retirement account that holds Bitcoin itself rather than funds or stocks. It’s a type of self-directed IRA, with the same tax rules as any Traditional or Roth IRA.
Forbes: “Self-directed IRAs let you invest in alternative assets like cryptocurrency, real estate, precious metals, and collectibles, all of which are excluded from conventional IRAs. The Retirement Industry Trust Association (RITA), a self-directed IRA industry group, estimates that 3% to 5% of all IRAs are invested in alternative assets.”
Like regular IRAs, Bitcoin IRAs come in Traditional and Roth versions. A Traditional IRA can defer taxes on contributions until you withdraw; a Roth IRA takes after-tax dollars and grows tax-free. A Bitcoin IRA is different from holding a spot Bitcoin ETF in a brokerage IRA: you own Bitcoin, not fund shares, and you don’t pay an annual fund fee.
For 2026, you can contribute up to $7,500 to your IRAs, up from $7,000 in 2025. If you’re 50 or older, you can add a $1,100 catch-up contribution, for $8,600 in total, according to the IRS.
Roth IRA contributions phase out between $153,000 and $168,000 of income for single filers and heads of household, and between $242,000 and $252,000 for married couples filing jointly. High earners above those limits sometimes use a backdoor Roth.
Rollovers and transfers from existing retirement accounts don’t count toward these limits.
Swan is a Bitcoin-only company founded in 2019. Its Bitcoin IRA lets you buy and hold Bitcoin in a Traditional or Roth IRA, and Swan says it’s trusted by more than 120,000 investors.
Trading fee: 1% on Bitcoin buys and sells, paid from IRA funds (Swan fees)
Platform fee: 0.02% of assets on platform a month, with a $20 minimum, charged from funds outside your IRA per IRS rules
Setup, transfer, rollover, wire and closure fees: $0
Account minimum: none
Traditional and Roth Bitcoin IRAs
Transfers from an existing Traditional, Roth, SEP or SIMPLE IRA
Rollovers from an old 401(k) or 403(b)
Swan says like-for-like transfers and rollovers carry no taxes or penalties. Our guide to rolling over a 401(k) to a Swan Bitcoin IRA walks through the steps. If you’re moving more than $50,000, Swan’s Private team helps with the transfer.
Swan’s IRA custodian is Equity Trust, a South Dakota regulated IRA custodian serving clients since 1984. Across its other account types, Swan works with BitGo Trust and Bakkt (Swan custody).
Pros
Bitcoin only: no altcoins to sort through.
No setup or transfer fees, and no account minimum.
Rollovers without taxes or penalties on like-for-like moves.
Strong reviews: 4.2 out of 5 on Trustpilot from 1,376 reviews and 4.8 out of 5 on the Apple App Store, as of October 26, 2026.
Cons
Bitcoin only, if you want other assets in the same IRA.
A monthly platform fee with a $20 minimum, which weighs more on small balances.
Swan’s custodian holds the keys, so you don’t hold them yourself while the Bitcoin is in the IRA.
Customer: “The best company for buying Bitcoin. Support is great.”
Customer: “Hard to say what I love most about Swan, is it the easy to set up dca? The automatic withdrawal to my hardware wallet? Or the easiest way to give the gift of bitcoin to a family member? All of this and a support team that has your back should you have a question.”
Customer: “These guys are top-notch. Passionate. Caring. Smart, Effective. I trust them wholeheartedly with my investments.”
Customer: “Swan has been the most reliable way to buy bitcoin over the years, and their bitcoin-only mission puts them in a category of their own. They always exceed my expectations, and the app experience is no different! Swan is the only exchange I feel comfortable recommending to friends and family.”
Customer: “Everyone at Swan is so helpful! Whenever I have a question, I can be sure that they will respond to my emails promptly and personably. They are always working to educate everyone more about bitcoin and make it easier to purchase it and take self-custody.”
Unchained is a Bitcoin-only financial services company. Its IRA holds your Bitcoin in multisig cold storage, and you control two of the three private keys.
Trading fee: 1.5% per transaction
Account fee: $250 per IRA account a year
Setup fee: none
Minimum: $2,000 to trade for each transfer, rollover or annual contribution
Unchained also sells an optional retirement service package at an extra cost (Unchained pricing).
Traditional, Roth and SEP IRAs, plus Solo 401(k)s through an Unchained Business account
Rollovers from an employer 401(k), 403(b) or TSP, or transfers from another IRA
IRA custodian: Fortis Bank
Pros
You hold keys: you control two of the three multisig keys, which Swan’s IRA doesn’t offer.
More account types, including SEP IRAs and Solo 401(k)s.
A flat yearly fee, which costs less than a percentage fee on large balances.
Cons
Higher trading fee: 1.5% per transaction.
$2,000 trading minimum for each transfer, rollover or contribution.
You’re responsible for your keys, which takes more care than a fully custodial IRA.
Few public reviews: 3 on Trustpilot and 74 ratings on the Apple App Store (4.8 out of 5) as of October 26, 2026.
Customer: “Great company, I’ve been a customer since 2021. Though they offer a free service, I opted for concierge onboarding and also opted for their inheritance option. I also plan to move my tradition and Roth IRAs to Unchained in the near future.”
Customer: “Very clean app — meticulously designed for the cleanest UX to track your portfolio, view products, deposit, and trade on the go. Buying directly to cold storage from a mobile app is surreal.”
Customer: “Included photo identification as requested (California DL) only to be told they couldn’t use state ID.”
Here’s what each IRA costs in the first year and each year after, for a one-time purchase at three sizes. These are our calculations from each company’s published fees, assuming a flat Bitcoin price and no further trades. They leave out Unchained’s optional service package.
$10,000: Swan costs $340 in year one ($100 trading fee plus $240 in monthly platform fees at the $20 minimum), then $240 a year. Unchained costs $400 in year one ($150 trading fee plus $250), then $250 a year.
$50,000: Swan costs $740 in year one ($500 plus $240), then $240 a year. Unchained costs $1,000 in year one ($750 plus $250), then $250 a year.
$250,000: Swan costs $3,100 in year one ($2,500 plus $600 in platform fees at 0.02% a month), then $600 a year. Unchained costs $4,000 in year one ($3,750 plus $250), then $250 a year.
For more on what to watch for, read our guide to Bitcoin IRA fees and the right questions to ask to avoid Bitcoin IRA icebergs.
No. River doesn’t offer an IRA of its own. River’s retirement guide describes a self-directed IRA set up as an LLC through Rocket Dollar, which then buys and holds Bitcoin at River, but adds that “River has no formal affiliation with Rocket Dollar. This is a partnered solution that clients have previously utilized when setting up a Self-Directed IRA LLC” (River).
Reasons to open a Bitcoin IRA
Tax treatment: you get the same tax benefits as any Traditional or Roth IRA.
Long-term focus: early withdrawal penalties encourage you to hold through volatility.
Diversification: Bitcoin adds an asset to a retirement portfolio that’s built on stocks and bonds.
Reasons to be careful
Volatility: Bitcoin’s price can fall sharply, which matters more as you near retirement.
Fees: setup, trading, custody and platform fees vary widely between providers. Read the fine print, or see our comparison of Bitcoin IRA providers.
Rules and regulation: IRA rules and Bitcoin regulation can change, so stay informed.
Bitcoin only: many retirement platforms push altcoins, which depend on a company or foundation to survive. Read our five reasons to focus on Bitcoin only.
Custody: know who holds your Bitcoin and who the IRA custodian is. Here’s why Bitcoin custodians matter.
Total fees: add up trading, platform, account and setup fees for your balance, as in the comparison above.
Rollovers: check whether transfers and rollovers are free and handled for you.
Reviews and support: look at Trustpilot and app store ratings, and the number of reviews behind them.
Your own risk tolerance: a Bitcoin IRA can be one part of a retirement portfolio. Consider talking with a financial advisor.
For the bigger picture, read why Bitcoin is the ultimate asset for your IRA, and how Peter Thiel built a $5 billion Roth IRA.
While we’re biased, we think Swan is the best possible way to own Bitcoin in a tax-advantaged retirement account such as a Traditional or Roth IRA: Bitcoin only, no setup or rollover fees, and a team that handles the transfer for you. If you’d rather hold your own keys and are comfortable managing them, Unchained is the Bitcoin-only alternative.
Hold your IRA with the most trusted name in Bitcoin.
For a Bitcoin-only IRA with no setup or rollover fees, we recommend the Swan Bitcoin IRA. If you want to hold two of the three keys yourself, the Unchained IRA is the main alternative.
Swan charges 1% on Bitcoin buys and sells, plus 0.02% of assets on platform each month with a $20 minimum. There’s no setup, transfer, rollover or closure fee.
Yes. Swan accepts rollovers from old 401(k) and 403(b) plans and transfers from Traditional, Roth, SEP and SIMPLE IRAs, and says like-for-like moves carry no taxes or penalties.
With Unchained, yes: your IRA’s Bitcoin is held in multisig cold storage, and you control two of the three keys. In Swan’s IRA, the custodian holds the Bitcoin. Outside an IRA, you can withdraw Bitcoin from Swan to your own cold storage at no cost.
No. River doesn’t offer its own IRA. Its guide describes a self-directed IRA LLC set up through Rocket Dollar, with which River says it has no formal affiliation.
Strike doesn’t list an IRA on its website, as of October 26, 2026.
Up to $7,500 in 2026, or $8,600 if you’re 50 or older. Rollovers and transfers from other retirement accounts don’t count toward the limit.
Swan Bitcoin IRA page (linked above), fees, account types and custodian, checked October 26, 2026
Unchained IRA and Unchained pricing, checked October 26, 2026
IRS: 2026 401(k) and IRA limits, November 13, 2025
Trustpilot: Swan Bitcoin and Unchained, checked October 26, 2026
Swan’s calculations: fees from each company’s published pricing, assuming a flat Bitcoin price and a single purchase.
This article is provided for educational purposes only, and cannot be relied upon as tax, accounting, legal, investment, or other advice. Past performance is not indicative of future performance. Bitcoin is a young, volatile, risky asset, and sudden large and sustained drops in price may occur from time to time.
Swan makes no representations regarding the performance, tax consequences, or investment suitability of any structure described herein, and all such questions should be directed to a relevant advisor of your choice.
The Bitcoin Retirement Calculator is only intended to show the projected investment performance based on parameters set by you, and in using this tool, you acknowledge that the results generated by placing various parameters through this tool are only projections of hypothetical performance that may be useful in assisting you in deciding how best to potentially incorporate a Bitcoin allocation in your IRA.
Matt Ruby is a seasoned content writer helping educate million worldwide about Bitcoin for Swan. Matt work with tech companies to create words, videos, and other content that makes them seem human. He specializes in taking boring/drab tech topics and making them interesting, educational, funny, and accessible to regular people.
In this article
Thoughts on Bitcoin from the Swan team and friends.
How Swan built an agentic software factory that finds production bugs, reaches consensus on the fix, opens the PR, and proves it works before a human merges.
Total federal debt crossed $40 trillion last week. Jeremy Showalter maps how we got here, where four institutional projections take it by 2050, and why the honest total is already about $55 trillion.
From entropy and SHA-256 to proof of work and the 21 million cap: a first principles guide to how Bitcoin works, and what you can verify yourself.